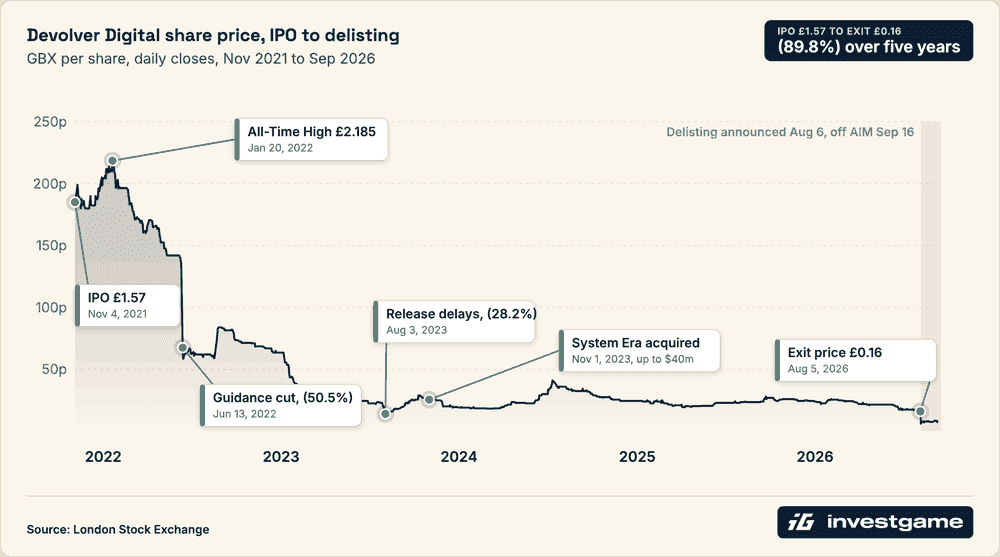
Devolver Digital leaves AIM at £0.16 a share, five years after a £1.57 IPO, at ~0.6x revenue

US-based indie games publisher Devolver Digital (AIM: DEVO) is leaving the London stock market. Shareholders voted 90% in favor of canceling the AIM listing from Sep 16, 2026. Alongside the vote, Devolver bought back 4.71% of its shares for $5.0m (GBP 3.7m). The founders, CEO Harry Miller, COO Graeme Struthers, and Nigel Lowrie, hold 31.45% pre-offer, rising to about 33% after the buyback completion. The exit was offered to everyone else at £0.16 per share. That was the closing price on Aug 5, the day before the plan was announced, so at spot with no premium. Shareholders tendered more shares than the $5.0m could purchase, so the offer was scaled back, and each seller sold only part of their holdings. Devolver’s shares are no longer quoted on a public market. A second buyback of up to $5.0m is planned within a year.
The board explains the decision with three reasons:
- Listing costs of ~$1.6m a year.
- A share that barely traded, ~33,000 shares a day in the three months before the announcement.
- A valuation that the directors say does not reflect the business.
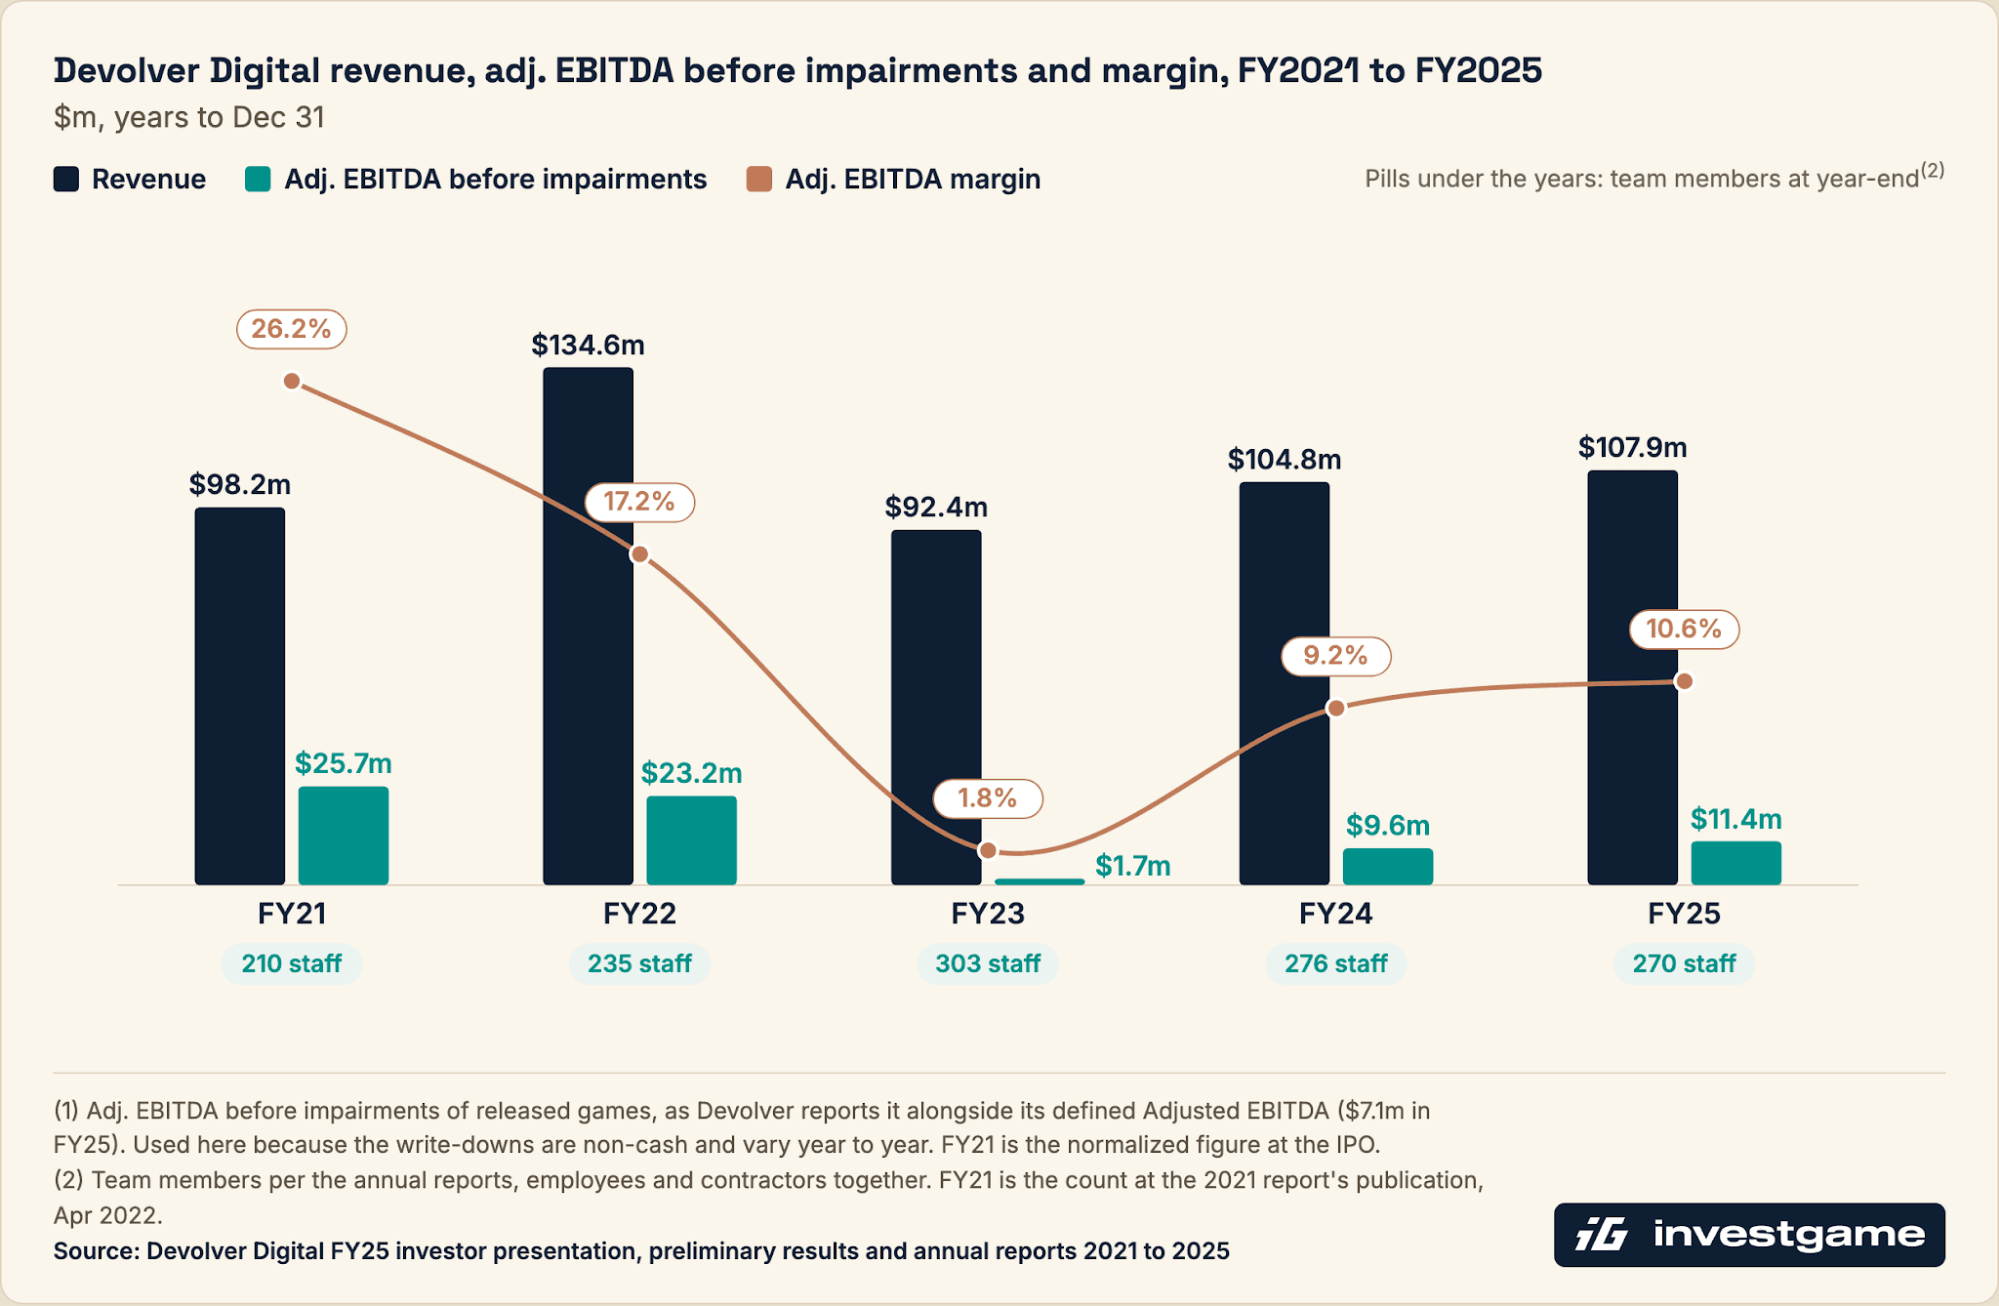
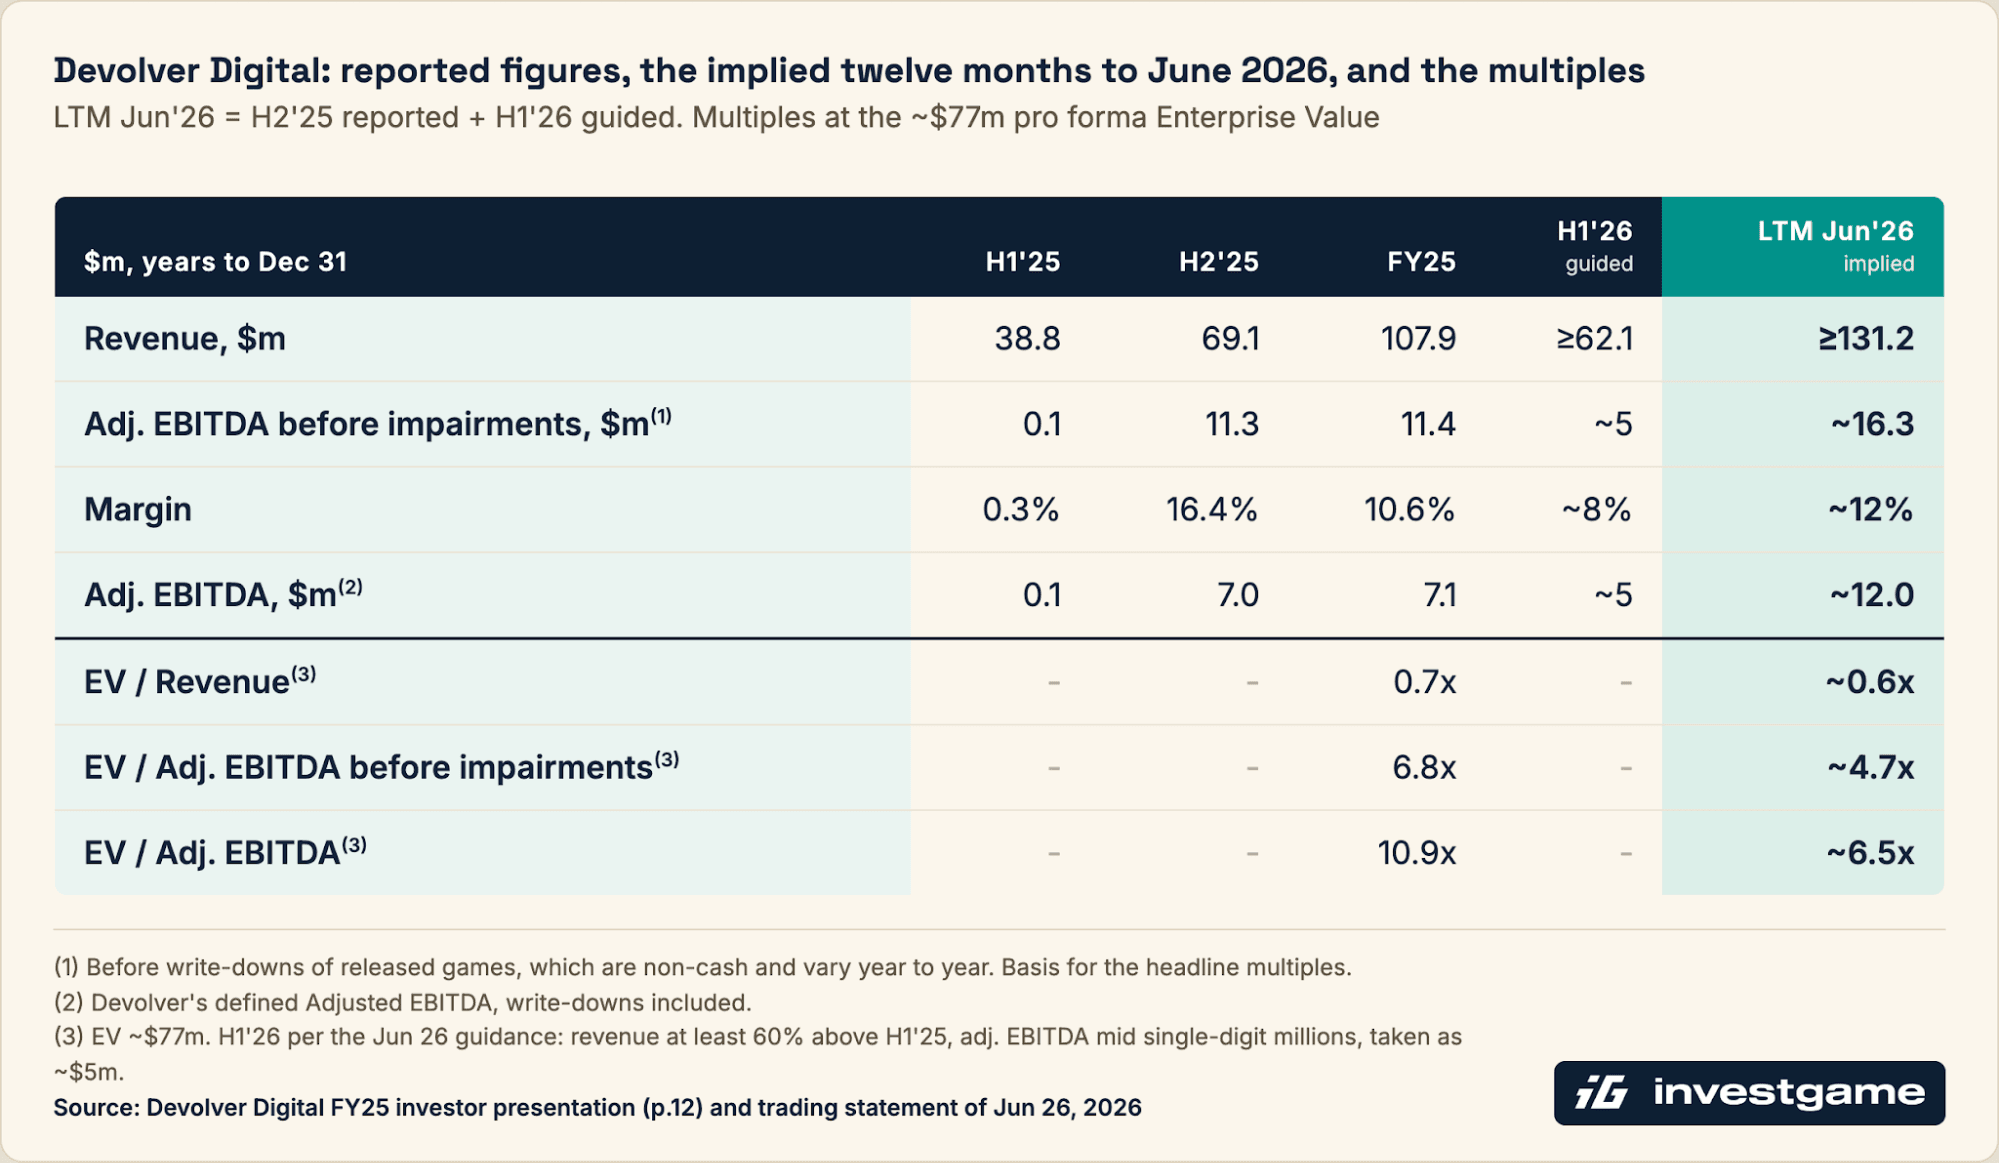
At £0.16 per share, Devolver’s equity is valued at $102.0m (GBP 75.6m). The latest reported balance sheet, as of Dec 31, 2025, shows $36.6m of cash and no debt. Since then, Devolver has paid $4.9m in cash toward System Era’s deferred consideration, with a further $2.1m remaining payable in cash and shares. On that pro forma basis, the Enterprise Value is ~$77m. Against FY25 revenue of $107.9m, that is 0.7x EV/Revenue, and 6.8x adj. EBITDA of $11.4m before impairments (10.9x on the $7.1m defined adj. EBITDA, which includes impairments). The business has moved on since: a Jun 26 trading update guided H1’26 revenue at least 60% above H1’25’s $38.8m, with adj. EBITDA in the mid-single-digit millions. That implies that through Jun 30, 2026, there will be at least $131m in revenue and ~$16m in adj. EBITDA, so ~0.6x revenue and ~4.7x adj. EBITDA.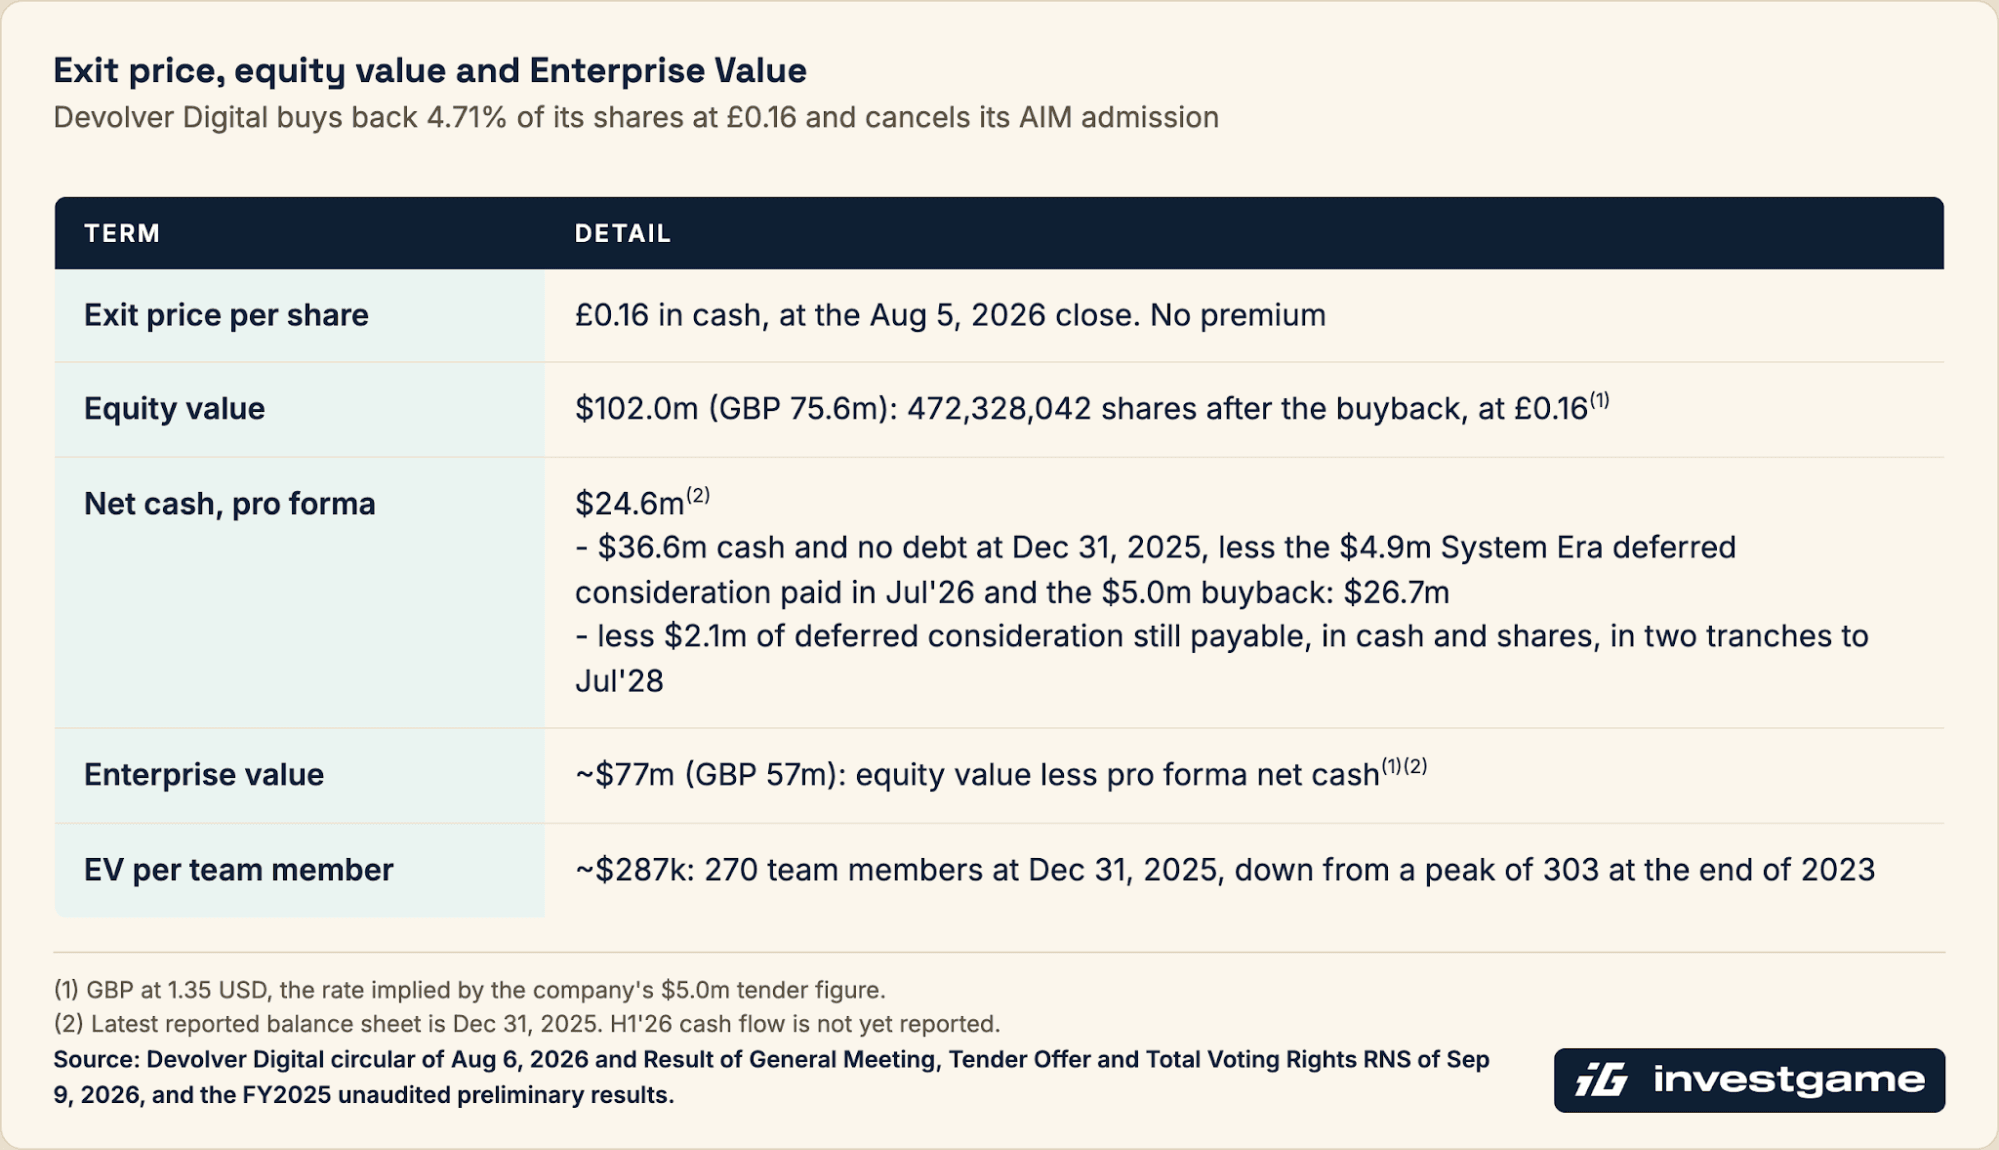
The share price tells the operating story. Revenue peaked in FY22, the year after the IPO, at the tail of the pandemic boom in premium PC & Console games. It fell by a third in FY23 as the release slate thinned, and the shares lost most of their value in those two years. Cash went into the System Era acquisition in Nov’23, $22m upfront and up to $40m in total, for the studio behind Astroneer. It also went into a heavier pipeline of own-IP games, which Devolver capitalizes on and releases over several years. The back catalog, which accounts for most of the revenue, grew by 20% in 2024 but has been shrinking in alternating years. New releases carried FY25 instead. Fifteen launches led by the roguelike BALL x PIT more than tripled front-catalog revenue and made H2’25 the strongest half of adj. EBITDA since 2022. That recovery arrived after the market had stopped paying for it. Headcount followed the same arc. The group had 210 team members around the IPO and 303 at the end of 2023, after System Era added 56. It ended 2025 with 270, after cuts at Nerial, Artificer, and Good Shepherd. The exit values Devolver at ~$287k of Enterprise Value per team member.